How to Read Your CIBIL Report: A Section-by-Section Guide

Most people open their CIBIL report for exactly one reason: to check the score. They see something like 780, feel relieved, and close the tab. Job done, right?
Except that's not even close to how a bank actually reads it.
When a loan officer pulls up your CIBIL report, your score is genuinely the last thing they look at. What they read first is everything else, your personal details, your loan history, how you've behaved with your EMIs, and a few specific remarks buried in the report that can quietly kill your loan application before the score is even considered. This catches people completely off guard sometimes, a strong score, a rejection anyway, and no idea why until they actually open the report.
So if you've ever wondered why someone with a solid 780 score still got rejected, the answer is almost always sitting somewhere inside the report, not in the number itself.
This guide walks you through the report exactly the way a bank does, section by section.
Here's a quick reference before we get into the detail, worth bookmarking if you'd rather scan than read top to bottom:
| Section | What to Check |
|---|---|
| Personal Details | Name, date of birth, gender, must match your PAN exactly |
| Identification Details | PAN and other linked IDs |
| Address History | Any address you've genuinely never lived at |
| Contact Details | Phone numbers or emails you don't recognise |
| Accounts | Loans, cards, current balance, overdue amounts |
| Payment History | DPD codes and your month-by-month repayment pattern |
| Credit Facility Status | Settled, Written-off, Suit Filed, or Post (WO) Settled remarks |
| Enquiries | How many lenders pulled your report, and how recently |
The First Page Isn't Just About the Score
Start by pulling your CIBIL report from the official TransUnion CIBIL website. If you haven't done this before, we've covered the exact steps in our guide on downloading your free CIBIL report.
The very first page shows your CIBIL score, a control number, and the date the report was generated.
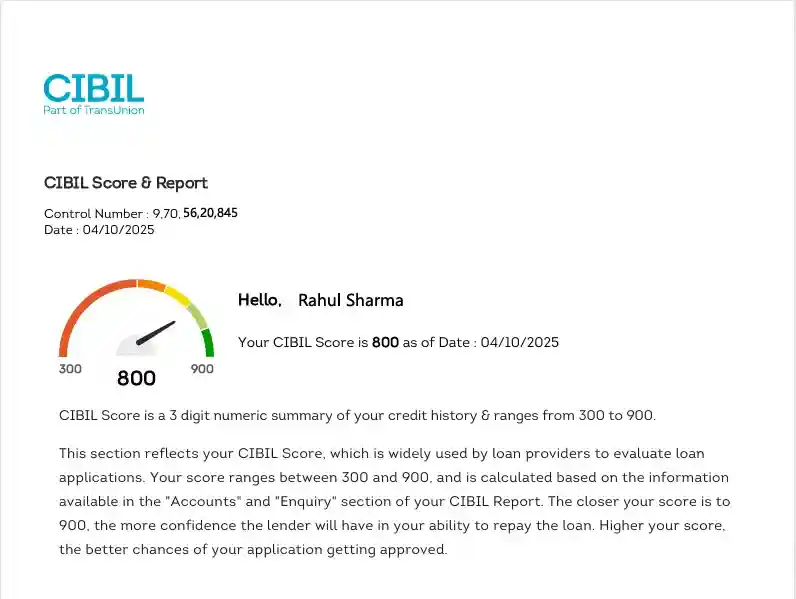
That control number matters more than people realise, it's essentially the reference ID for this exact report. If you ever raise a dispute later, this is the number that ties everything back to this specific version of your file.
As for the score, anywhere from 300 to 900, think of it as a summary line, not the story itself. An 800 looks great on paper, but it's simply a reflection of everything documented further down. The real reading starts after this page.
Personal Details: Where Small Mistakes Cause Big Problems
This section looks harmless enough, just your name, date of birth, and gender. But it's also where a surprising number of approval delays begin.
If your name here doesn't quite match your PAN records, or your date of birth is off by even a digit, banks can struggle to verify your identity cleanly. That mismatch alone is enough to trigger extra verification steps or slow down your loan process, even when nothing else in your file is wrong.
Identification Details: Why PAN Is the One That Matters Most
Next you'll find your linked ID documents: PAN, Voter ID, Driving Licence, sometimes even Ration Card. Out of all of these, your PAN carries the most weight, and it's not close.
Your whole credit history is essentially built around your PAN number. If it's entered wrong, or worse, if someone else's loan somehow got linked to your PAN, your entire report becomes unreliable. This is genuinely one of the most serious issues people stumble on when they finally sit down and read this section properly, so check it carefully, don't just skim past it.
Address History: Old Addresses Are Normal, Strange Ones Aren't
This part tends to catch people off guard. You might see addresses from 10 years back, an old office address, or a rented flat you've completely forgotten about.
That's actually expected, banks report whatever address they had on file at the time you opened that particular account. Old addresses are normal. What's not normal is seeing an address you've genuinely never lived at. That's a real warning sign, and it usually means someone else may have used your identity to open a line of credit somewhere. Treat this one as a priority check, not a curiosity, it's one of the clearer tells of a genuine identity issue hiding in an otherwise normal-looking report.
Contact Details: The Section Most People Skip (And Shouldn't)
Here you'll find old phone numbers and email addresses you gave to various banks over the years while applying for loans or cards.
If a number shows up that you simply don't recognise, that's worth paying attention to, it can mean your information was used somewhere without your knowledge. Most people scroll right past this section. Lenders don't.
Employment Details: Small Field, Still Worth a Glance
This just shows whether you were marked as salaried or self-employed at the time you applied for that particular credit line. Doesn't sound like much, but it does help banks build a picture of your overall financial profile.
The Real Meat of the Report: Your Accounts Section
This is where a bank actually spends most of its time.
Every loan and credit card you've ever held, active or closed, shows up here, along with detailed history on how you've handled each one. You'll see the lender's name, the type of credit, when it started, the sanctioned amount, your current balance, and your EMI.
But a careful reader doesn't stop at the surface details. They dig into a few very specific fields.
What Banks Actually Zoom In On
When a bank officer opens this section, their eyes go straight to the current balance, the amount overdue, the date of last payment, when the account was last reported, and the EMI amount.
If that "Amount Overdue" field isn't showing zero or blank, that's an immediate red flag for them.
They'll also check how recently the account was updated. An account that hasn't been touched or reported in months can itself raise questions.
Credit Facility Status: The One Line That Can Quietly Wreck Your Application
In most healthy accounts, this field is simply blank. That's exactly what you want to see.
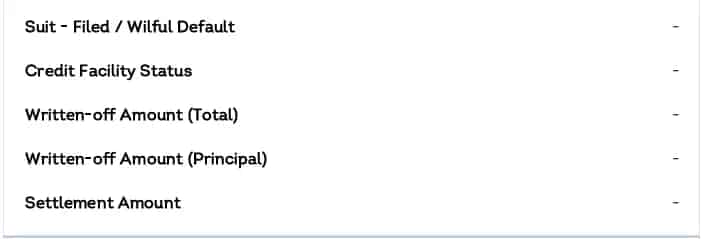
But if there's anything written here, take it seriously, this is one of the heaviest fields in the entire report.
- Settled: means you didn't repay the full loan amount, you negotiated a lower payoff. Banks treat this almost the same as an outright default.
- Written-off: the lender has officially declared that amount a loss on their books.
- Suit Filed: legal proceedings were initiated against you.
- Post (WO) Settled: the loan was first written off, then partially recovered later.
These remarks aren't temporary either, they sit on your report for years and can affect approvals even when your score itself looks perfectly healthy.
Written-off Amount: A Quiet But Serious Marker
If you spot numbers under "Written-off Amount (Total)" or "Written-off Amount (Principal)", it means the lender has already recorded part of that loan as unrecoverable in their books.
And here's the part people often miss, even if you go back and repay it in full later, this marking doesn't disappear on its own. It needs to be corrected separately.
Payment History: Your Month-by-Month Report Card (Understanding DPD)
This is, without question, the most scrutinised part of the whole report.
Every single month gets a code showing exactly how you handled that period's EMI or credit card bill, codes like STD, SMA, SUB, DBT, or straight numbers like 030, 060, 090.
Behind all of this sits one core concept: DPD, or Days Past Due, simply the number of days your payment was late that month.
- STD (Standard): paid right on time, DPD = 000, exactly what you want
- 030: 30 days late
- 060: 60 days late
- 090: 90 days late
- SMA (Special Mention Account): an early warning stage, before things turn into a real default
- SUB (Sub-standard): account has stayed overdue for a fairly long stretch
- DBT (Doubtful): high chance the lender won't recover this amount
- LSS (Loss): considered a lost cause by the lender at this point
Even a single 030 entry is enough to make a lender pause and think twice.
But once DPD crosses 90, showing as 090, SUB, DBT, or LSS, it becomes a genuinely serious red flag, especially on unsecured credit like personal loans and credit cards. Public sector banks in particular tend to weigh this very heavily, since it signals an actual pattern of repayment stress, not a one-off slip.
Banks aren't glancing at your score in this section, they're reading it line by line, month by month, building a picture of how disciplined you've really been.
A long, clean run of STD entries builds serious trust over time. But it doesn't take much to undo it, a few bad months of high DPD can outweigh years of good behaviour.
Collateral and Legal Status
If you've taken a secured loan, this part shows the property value and type of collateral involved.
Watch out for anything marked "Suit Filed" or "Wilful Default" here, both are serious legal red flags that lenders take very seriously.
Enquiry Section: Why Applying Everywhere at Once Backfires
Towards the bottom, you'll find your enquiry history, a record of which banks pulled your report, and why.
If a bunch of lenders checked your file within a short window, it signals to future lenders that you're aggressively hunting for credit. That pattern alone can lower their confidence in approving you, regardless of what your score says.
So How Do Banks Actually Read the Report?
Not top-down by score, that's for sure. In practice, the order usually runs from Credit Facility Status, to payment history and DPD pattern, to any overdue amounts, to Settled or written-off remarks, and finally to recent enquiries. Only after going through all of this do they actually glance at the score, almost as a final confirmation, not a starting point.
Why It's Worth Reading the Whole Thing, Not Just the Score
A lot of people walk around with genuinely good scores while completely unaware of a "Settled" remark or an old late payment sitting quietly in their file. These small, easy-to-miss lines are exactly what cause unexpected loan rejections.
Making it a habit to read your full report once a year means you catch these issues before a bank does, and while there's still time to fix them.
Final Thought
Your CIBIL report isn't just a document sitting in a folder somewhere, it's basically your financial reputation, written down in detail.
Once you learn to actually read it the way lenders do, you stop guessing why an application got rejected. You start seeing your own credit profile with the same eyes a bank uses.
And once that clicks, you'll never look at just the score again.
Frequently Asked Questions
My score is already above 750, do I really need to read through the whole report?
Worth doing anyway. The score is a summary of everything else in the report, not a substitute for it. Plenty of people carry a solid score while a "Settled" remark or an old high-DPD month sits quietly further down, completely unaffecting the number a bank sees first but very much affecting what a loan officer reads once they dig in.
My loan got rejected even though my score looked fine, what should I actually check first?
Start with the Credit Facility Status field on your accounts, not the score. That's genuinely where banks look first, and it's the field most people don't even know exists. From there, work through the payment history for any DPD entries crossing 90 days, then check the amount overdue on each account.
Does one late payment really matter, or is it only a problem if it happens repeatedly?
A single 030 entry, 30 days late, is usually enough to make a lender pause, even if it was a one-off. It doesn't automatically sink an application the way a 90-plus DPD or a Settled remark would, but it's not invisible either. A long clean run of STD entries can absorb one slip, several bad months in a row is a different story.
I found an old address in my report that I don't recognise at all, is that something to worry about?
Yes, that's worth taking seriously. Old addresses tied to accounts you remember opening are completely normal, banks just report whatever was on file at the time. An address you've genuinely never lived at is different, and it's often a sign that your identity was used to open a line of credit you don't know about.
Why do multiple loan enquiries in a short period hurt me if I've never missed a payment?
Because lenders read a cluster of recent enquiries as a sign you're actively chasing credit from multiple places at once, regardless of your repayment record. It doesn't mean automatic rejection, but it does lower confidence, since it's genuinely hard for a bank to tell the difference between someone comparing rates and someone in financial trouble applying everywhere at once.
Does a Written-off or Settled remark eventually fall off the report on its own if I just wait it out?
No, and this is one of the more common misunderstandings people have. These remarks sit on your report for years and don't self-correct, even after you've repaid the amount in full. The status has to be corrected separately once the dues are cleared, we've covered the exact process for both Written-off and Settled status in separate guides.